Bought in 2020–2022? You May Have More Options Than You Think
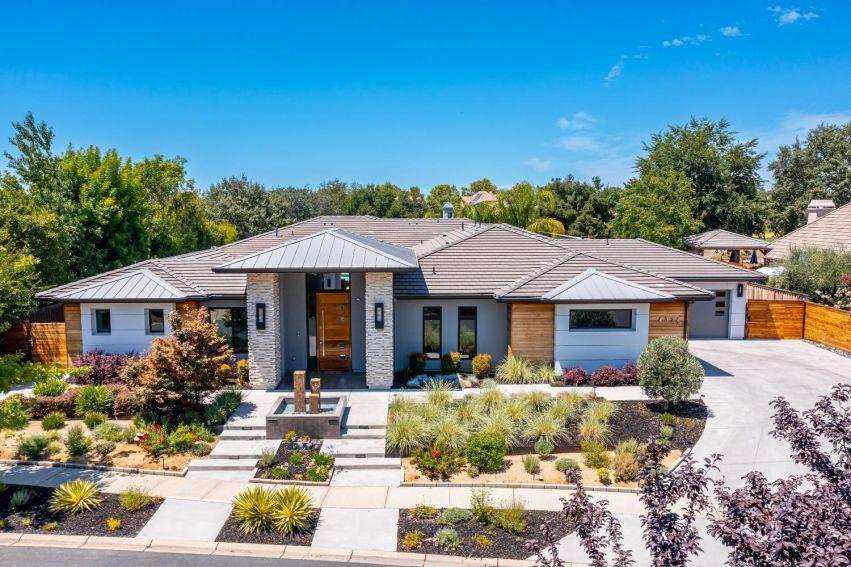
If you bought a home between 2020 and 2022, there's a good chance you've built equity over the years. But even if your property is worth more today, you may feel hesitant to make a move.
Why? Your mortgage rate.
Many homeowners who purchased during that period secured historically low interest rates. With today's mortgage rates potentially much higher, moving into another home can feel like giving up a financial advantage that's difficult to replace.
But keeping your current mortgage rate doesn't have to mean staying in the same home forever. Depending on your equity, finances, and long-term goals, you may have more options than you realize.
For homeowners in Sacramento, Folsom, El Dorado Hills, and Fair Oaks, here are three possibilities worth exploring.
First, Understand How Much Equity You've Built
Home equity is the difference between your property's current market value and the amount you still owe on your mortgage.
For example, imagine you purchased a home in Folsom in 2021 for $600,000. Today, let's say its estimated market value is $725,000 and your remaining mortgage balance is $520,000.
Your estimated equity would be $205,000.
That's a useful starting point, but it doesn't mean you would receive $205,000 in cash if you sold. Selling expenses, your loan payoff, and any other obligations would affect your actual proceeds.
Property values also vary by neighborhood, property condition, and recent comparable sales. A home in Broadstone may perform differently from one in Empire Ranch or another part of Folsom.
Before making a decision, get an updated estimate based on recent local sales rather than relying only on the original purchase price or an online estimate.
Option 1: Move Up to a Home That Fits Your Needs
Maybe your family has grown, you need another bedroom, or you're ready for a different neighborhood. If you've built equity, selling your current home could help fund your next purchase.
The equity from your sale may contribute toward a down payment, closing costs, or other expenses associated with buying another property.
For example, a homeowner selling a Sacramento property may use the proceeds to explore a larger home in El Dorado Hills or a different location in Folsom.
However, moving up requires looking beyond the sale price. Your new mortgage payment may be higher because of current interest rates, a larger loan amount, property taxes, insurance, and maintenance expenses.
Before listing, compare your estimated sale proceeds with the total cost of the home you want to buy. A lender can help you understand your financing options and determine a comfortable budget.
The goal isn't simply to purchase a more expensive property. It's to make sure the next home supports your lifestyle and financial plans.
Option 2: Access Your Equity Without Selling
What if you like your current home but need funds for another goal?
Depending on your financial situation and available equity, you may be able to explore ways to access some of the value you've built.
Possible options include a home equity loan, a home equity line of credit (HELOC), or a cash-out refinance.
A home equity loan generally provides a lump sum with a separate repayment schedule. A HELOC typically offers access to a revolving credit line, subject to its terms. A cash-out refinance replaces your existing mortgage with a new, larger loan and gives you the difference in cash after applicable costs.
There is an important consideration for homeowners with low mortgage rates: a cash-out refinance may replace your favorable existing rate with today's available rate on the entire refinanced balance.
A home equity loan or HELOC may allow you to keep your original first mortgage, but the additional borrowing still comes with interest, fees, and repayment obligations.
These options are not free money. Compare the total borrowing cost, monthly payments, and risks before using your home as collateral. Speak with a qualified lender or financial professional to understand which option, if any, makes sense.
Option 3: Keep Your Home as a Rental
Another possibility is to move into a new home while keeping your current property as a long-term rental.
This strategy may be worth considering if your existing mortgage has a favorable rate and the property can generate enough rental income to support its expenses.
For example, a homeowner in Fair Oaks might consider renting out a home rather than selling it when relocating to another area. The existing mortgage could remain in place, subject to the loan agreement and lender requirements.
But don't compare the mortgage payment with rent alone. Include property taxes, landlord insurance, repairs, maintenance, vacancy periods, management fees, and other operating costs.
Also review your mortgage documents and speak with your lender about occupancy requirements before converting a primary residence into a rental. Your insurance coverage may need to change as well.
If managing tenants and repairs isn't appealing, professional property management may help handle the day-to-day responsibilities.
Keeping the home could offer potential rental income and long-term appreciation, but it also means taking on landlord responsibilities and property-related financial risks.
Which Option Makes the Most Sense?
There isn't one answer for every homeowner. Your best option depends on what you want to accomplish.
- Move up if your current home no longer fits your needs and your equity can help make the next purchase financially comfortable.
- Access equity if you want to keep your home but need funds for a specific purpose and can manage the additional debt.
- Keep it as a rental if the numbers work, you can handle the responsibilities, and you want to explore long-term property ownership.
Remember, a low mortgage rate is valuable, but it should be considered alongside your equity, monthly expenses, lifestyle, and future plans.
Take a Fresh Look at Your Home's Value
If you purchased between 2020 and 2022, you may have more choices than you think. Understanding your current home value is the first step toward knowing what's possible.
Star Home Realty can help homeowners in Sacramento, Folsom, El Dorado Hills, and Fair Oaks review local market conditions and explore whether selling or keeping a property may better support their goals.
See what your home is worth today.
A current home value estimate can help you understand your equity and make your next real estate decision with greater confidence.
Disclaimer: This article is for general educational purposes only and is not financial, tax, legal, lending, or investment advice. Mortgage terms, rental rules, tax consequences, and financing eligibility vary. Consult qualified professionals before making financial or property decisions.