California Home Insurance Is Going Up: What Homeowners Can Do Now
If you own a home in California, you may have noticed your homeowners insurance premium increasing—or discovered that renewing your policy is becoming more difficult. Rising insurance costs are creating new challenges for homeowners across the state, including those in Sacramento, Folsom, El Dorado Hills, and Fair Oaks.
Home insurance is more than another household expense. It can affect your monthly budget, your ability to maintain a mortgage, and even the affordability of buying or selling a home.
The good news is that homeowners have options. Understanding why premiums are rising, how to compare coverage, and what the California FAIR Plan offers can help you make informed decisions about your property.
Why Is Home Insurance Getting More Expensive in California?
Several factors are contributing to rising homeowners insurance costs throughout California.
Wildfire risk and property damage
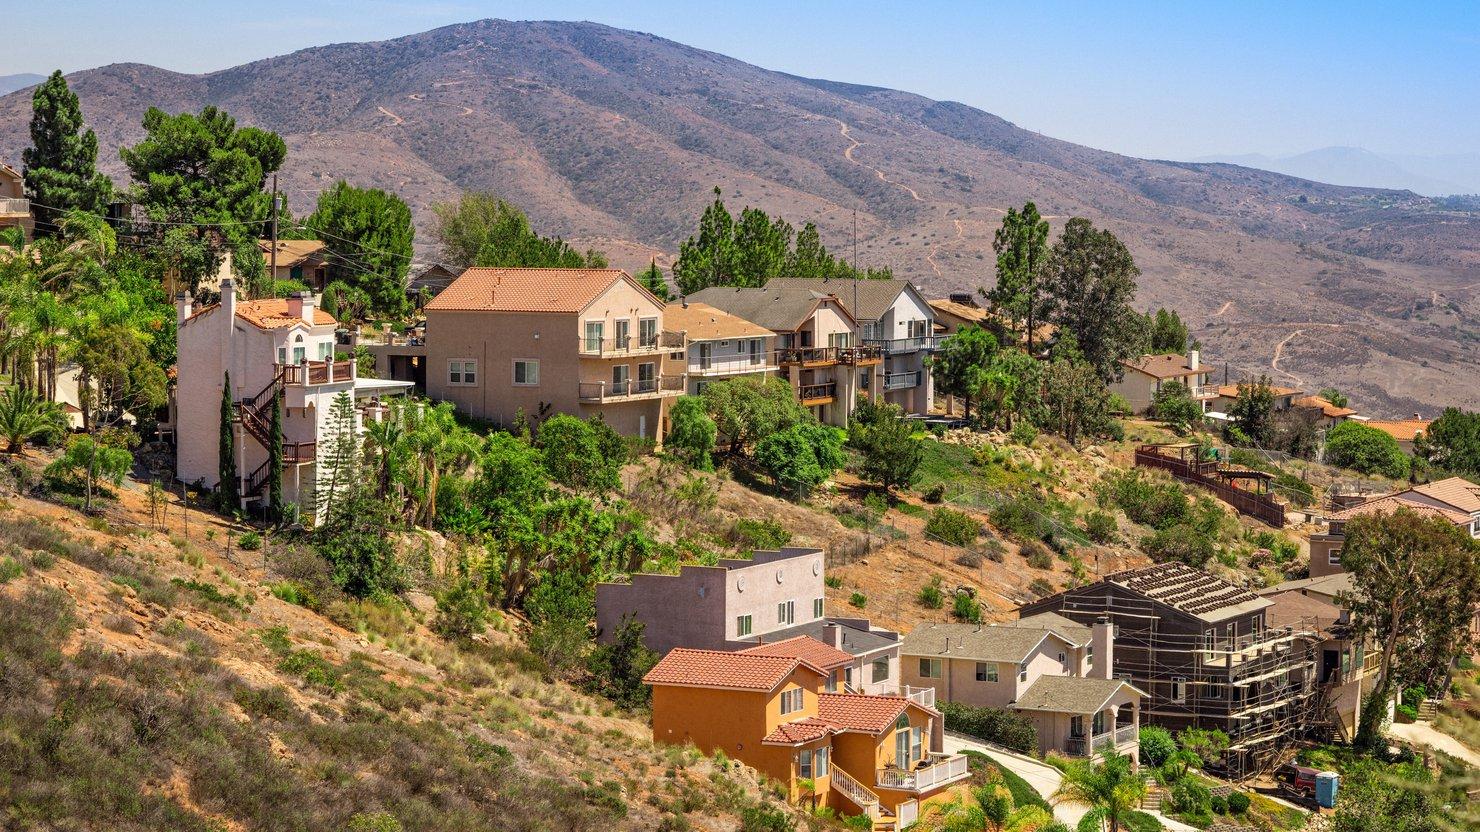
Wildfires can cause extensive damage to homes, neighborhoods, and infrastructure. Insurers consider the likelihood of a property experiencing a loss when setting premiums and deciding where to offer coverage. Homes in or near wildfire-prone areas may face higher costs or fewer insurance options.
This can be especially important for homeowners in parts of El Dorado Hills and the Sierra Nevada foothills, where local fire risk and a property's surroundings may affect insurance availability and pricing.
Higher rebuilding and repair costs
When a home is damaged, an insurance company may need to pay for labor, building materials, and specialized repairs. If construction costs rise, rebuilding the same home can become more expensive. Insurers may adjust premiums to account for these potential costs.
Expensive and increasingly complex claims
Wildfire losses can involve more than repairing a structure. Claims may include debris removal, temporary housing, and other covered expenses. Insurers also consider the cost of obtaining reinsurance, which helps them manage large losses.
Fewer insurance options in some areas
Some insurers have reduced new business or limited coverage in higher-risk parts of California. When fewer companies are willing to insure a property, homeowners may have a harder time finding competitive quotes.
According to the California Department of Insurance, the state is working to improve insurance availability through its Sustainable Insurance Strategy. However, individual premiums and coverage options still depend on the insurer, the property, and its risk factors.
Practical Ways to Lower Your Home Insurance Premium
You may not be able to control every factor affecting insurance prices, but there are steps you can take to review your costs and potentially improve your options.
Compare Quotes From Multiple Insurers
Don't automatically renew without checking what other insurers may offer. Contact a licensed insurance agent or broker and compare quotes for similar coverage, deductibles, and limits.
The lowest premium is not always the best deal. Make sure you understand exclusions, deductibles, liability protection, and how the policy pays for rebuilding your home.
California homeowners can also use the California Department of Insurance's insurance comparison resources to research available options.
Ask About Discounts
Ask your insurer which discounts may apply to your property. Depending on the company, savings may be available for qualifying home safety features, monitored security systems, certain fire-resistant improvements, or bundling eligible policies.
Discounts vary by insurer, so confirm the requirements rather than assuming a particular improvement will automatically lower your rate.
Reduce Wildfire Exposure Where Possible
If your home is in a wildfire-prone area, ask your insurer which mitigation measures it recognizes. Keeping gutters clear, removing dry vegetation near structures, maintaining defensible space, and using fire-resistant materials where practical can help reduce risk.
California's Safer from Wildfires program also encourages homeowners to take steps that make properties more resilient. Some insurers may recognize qualifying improvements when determining eligibility or discounts.
Before spending money on major upgrades, check which measures your insurer will actually recognize and whether documentation or an inspection is required.
Review Your Coverage and Deductible
Review your dwelling coverage to make sure it reflects realistic rebuilding costs—not simply your home's market value or purchase price. Land value is generally not part of the cost to rebuild the structure.
You can also ask how a higher deductible would affect your premium. A higher deductible may reduce the annual cost, but it means you must pay more out of pocket for a covered claim. Choose an amount you could reasonably afford in an emergency.
Avoid reducing essential protection just to get a lower price. Make changes only after understanding how they affect your coverage.
What Is the California FAIR Plan?
The California FAIR Plan is a safety-net option for property owners who cannot obtain coverage through the traditional insurance market. It is often called California's insurer of last resort.
It is important to understand that the FAIR Plan is not the same as a standard homeowners insurance policy. Its basic coverage is limited primarily to specified fire-related losses, including fire, lightning, smoke, and internal explosion. Additional coverage options may be available, but important protections—such as personal liability and theft coverage—are not automatically included in the basic FAIR Plan policy.
Some homeowners pair a FAIR Plan policy with a separate Differences in Conditions policy to help cover certain gaps. A licensed insurance professional can explain what combination of policies may fit your needs.
The FAIR Plan should generally be considered after you've made a serious effort to find coverage in the regular insurance market. If you need to explore it, work with an agent or broker registered to offer FAIR Plan coverage, and carefully compare the total cost and coverage limitations.
There is another important consideration for current policyholders: the FAIR Plan announced an average rate increase of 29.1%, effective October 15, 2026. That is an average, not a guaranteed increase for every customer. The actual change depends on the property and its risk profile.
If you're relying on the FAIR Plan, review your renewal documents and ask your broker whether additional private-market options are available.
How Higher Insurance Costs Affect Homebuyers
Insurance is becoming an increasingly important part of the homebuying budget.
When buyers evaluate a property in Sacramento, Folsom, Fair Oaks, or El Dorado Hills, they need to consider more than the mortgage payment, property taxes, and homeowners association fees. The annual insurance premium—and whether coverage is available at all—can affect the total cost of ownership.
A home with a high insurance premium may stretch a buyer's budget or reduce the amount they are comfortable offering. If a lender requires homeowners insurance, difficulty obtaining an acceptable policy can also complicate the financing process.
Buyers should request insurance quotes early, particularly before removing contingencies or making major financial commitments. Waiting until the last minute may leave too little time to compare options or address coverage problems.
Can Rising Insurance Costs Affect Home Values?
Insurance costs can influence buyer demand, but they do not automatically cause a home's value to fall.
If a property is expensive or difficult to insure, some buyers may decide to look elsewhere. Others may adjust their offers to account for higher ongoing expenses. In areas where insurance availability is a concern, buyers may also pay closer attention to fire-risk information, property improvements, and the cost of maintaining the home.
However, home values still depend on many factors, including location, condition, comparable sales, interest rates, inventory, and buyer demand. A property's insurance cost is one part of the overall picture—not a stand-alone valuation.
For sellers, being prepared can help. Gather available insurance information, document qualifying safety improvements, and be ready to discuss the property's features and maintenance history. Buyers should still verify coverage and costs directly with an insurer.
What Should California Homeowners Do Next?
Whether you're planning to stay in your home, buy a property, or sell in the coming year, start by reviewing your current insurance policy and exploring realistic alternatives before renewal. Ask questions, compare coverage carefully, and document any risk-reduction improvements.
For homeowners in Sacramento, Folsom, El Dorado Hills, and Fair Oaks, understanding insurance costs can help you plan your next move with greater confidence.
Thinking of selling? Ask how insurance affects your home’s value.
Star Home Realty can help you understand local market conditions and the factors buyers may consider when evaluating your property. Reach out to discuss your selling goals and request guidance on preparing your home for the market.
Disclaimer: This article is for general educational purposes only and is not insurance, legal, or financial advice. Coverage, eligibility, premiums, and discounts vary by property and insurer. Consult a licensed insurance professional for advice specific to your situation.